Updated September 1, 2026.
A contractor-controlled insurance program, commonly called a CCIP, is one form of controlled insurance program in which the general contractor sponsors specified insurance coverage for eligible enrolled participants on a project. It is not automatically better than coverage carried separately by each contractor, and it is not appropriate for every project.
The decision belongs with the owner, contractor, insurance broker, insurer and legal advisers using the actual program documents and project risk. This guide identifies questions construction teams should resolve; it does not recommend insurance or interpret coverage.
Start with the program definition
Controlled insurance programs may be sponsored by an owner or contractor. The program documents determine the covered project, policy periods, enrolled parties, coverage lines, limits, exclusions, deductibles, retained risk and administration requirements.
Do not assume that the label “CCIP” answers those questions. Obtain the insurance manual, policies, endorsements and enrollment requirements and have qualified insurance and legal professionals review them.
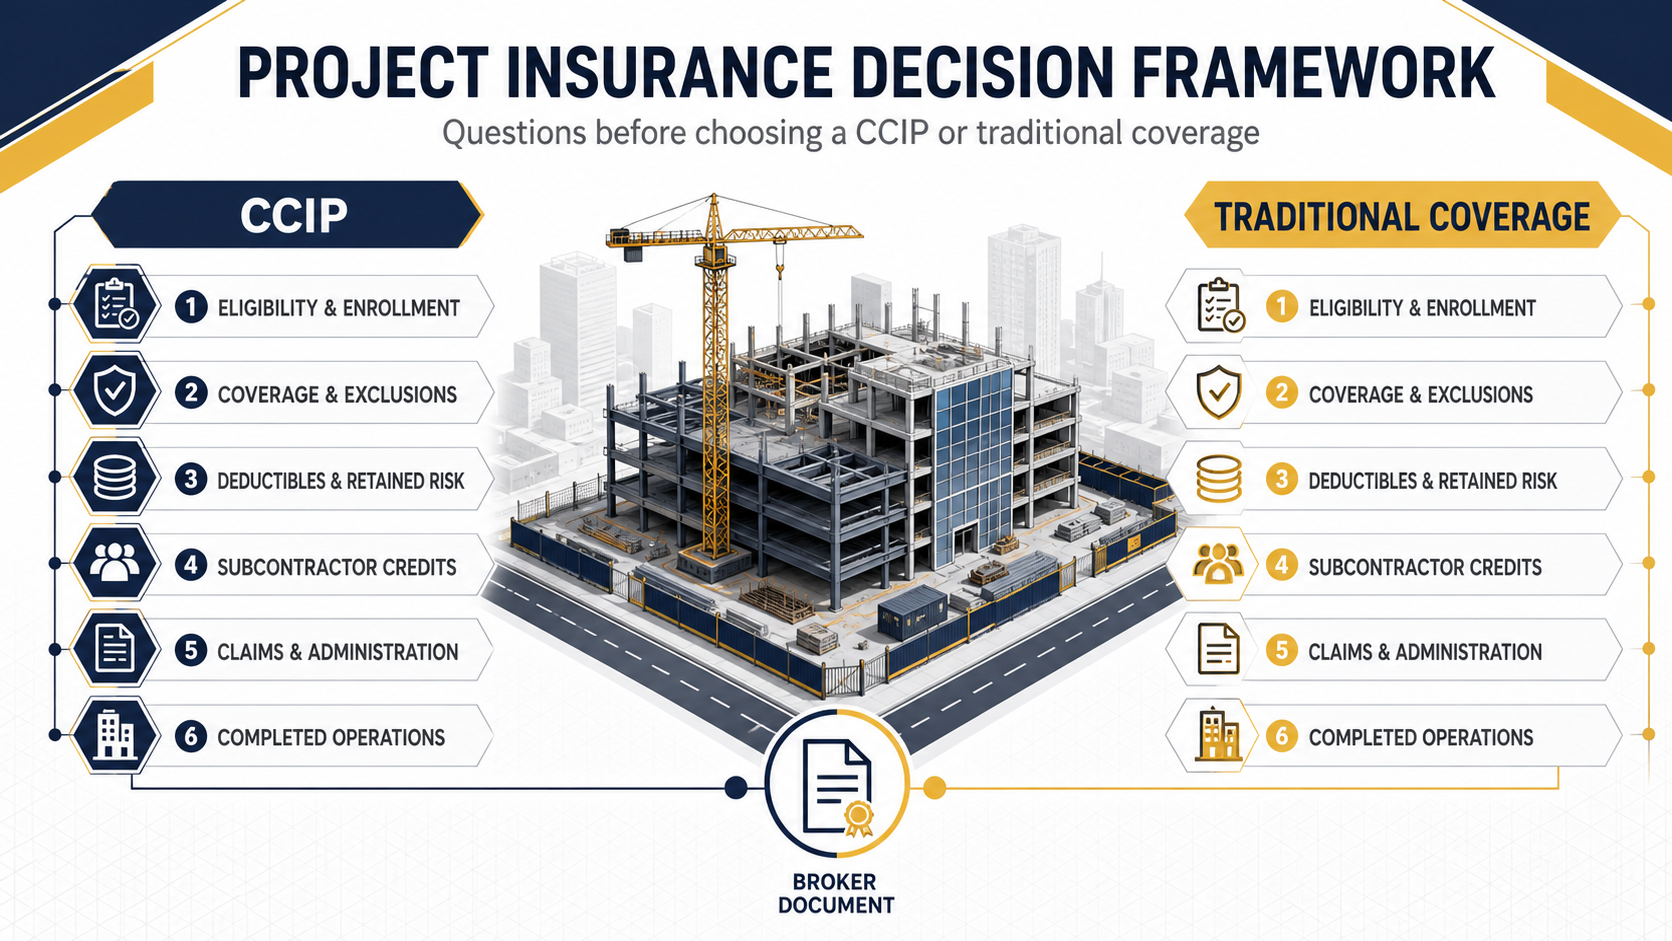
1. Eligibility and enrollment
Identify which contractors and subcontractors are eligible, excluded or required to enroll. Some categories of vendors, suppliers, professional services or off-site operations may be outside the program. Confirm when enrollment must occur, what information is required and how lower-tier subcontractors are handled.
A participant should not begin affected work based on an assumption that enrollment is complete. The administrator should provide the documentation required by the program.
2. Coverage lines, limits and exclusions
Determine which coverage lines the CCIP provides and which remain the responsibility of each participant. Review limits, aggregates, policy periods, territory, exclusions and requirements for automobile, professional, pollution, cyber, equipment or other exposures that may not be included.
Coverage interpretation must come from the policy documents and qualified advisers, not from a construction proposal or blog summary.
3. Deductibles and retained risk
Clarify who is responsible for deductibles, self-insured retentions, claim costs or other retained risk. Identify any contractual allocation to subcontractors and how that allocation is administered.
The project team should understand the process before a claim occurs. Financial responsibility and enforceability are legal and insurance questions requiring project-specific review.
4. Subcontractor insurance credits
Because specified project coverage may be provided through the CCIP, enrolled subcontractors may need to remove corresponding insurance costs from their bids. Establish a consistent method for identifying, documenting and reviewing those credits.
A credit should be based on the actual bid and program requirements, not a universal percentage. Contractors may still need separate coverage for excluded operations, other projects or risks outside the CCIP.
5. Claims and incident administration
Define how incidents are reported, who receives notice, which records are required and who coordinates with the administrator, broker and insurer. The process should also address preservation of evidence, return-to-work coordination where applicable and communication with affected employers.
IRMI notes that controlled insurance programs can present administrative challenges involving enrollment, payroll reporting, certificates, claims and coordination. Assign trained resources rather than treating administration as a minor clerical task.
6. Completed-operations coverage
Construction claims can arise after the work is complete. Review the completed-operations period, limits, exclusions, participant responsibilities and record-retention requirements. Confirm how coverage interacts with warranties and insurance maintained outside the program.
Do not assume that project completion or permit closure ends every reporting or documentation obligation.
Safety requirements remain operational responsibilities
A consolidated insurance structure does not transfer each employer’s safety responsibilities. Cal/OSHA’s employer-responsibility guidance identifies continuing duties such as maintaining an Injury and Illness Prevention Program, inspecting workplaces, correcting hazards and providing required training. Review the program’s safety requirements, reporting expectations, orientation and monitoring procedures, then integrate them with the site-specific plans and legal duties of the responsible employers.
Insurance may respond to specified losses; it does not replace hazard assessment, competent supervision, training or compliance.
Data, payroll and record controls
CCIP administration may require payroll, classification, contract, enrollment, certificate and loss information from multiple tiers. Establish who collects it, how accuracy is checked, where it is retained and how confidential information is protected.
At closeout, confirm that final payroll and subcontractor information has been submitted and that participants receive the documentation required by the program.
Questions to compare with traditional coverage
- Which participants and operations are covered or excluded?
- Which coverage lines remain outside the program?
- Who bears deductibles and retained risk?
- How are subcontractor insurance credits calculated and documented?
- Who administers enrollment, reporting and certificates?
- How are incidents and claims reported?
- What completed-operations coverage applies after construction?
- What staffing and systems are required to administer the program?
When to involve advisers
Insurance and legal advisers should review the program before contract execution and before participants rely on it. The construction team can help map the project organization, subcontracting plan, schedule and administrative workflow, but should not interpret policy language unless qualified and authorized to do so.
Constructive Solutions provides commercial preconstruction and commercial construction services for Bay Area projects. Insurance placement and coverage advice remain with the owner’s and contractor’s qualified brokers, insurers and counsel.
Sources
- IRMI: Controlled insurance program definition
- IRMI: Traditional versus project insurance
- IRMI: Common administration challenges in controlled insurance programs
- Cal/OSHA: Overview of employer responsibilities
This article is general construction-planning information, not insurance, legal, financial or risk-management advice. Coverage depends on the actual policies, endorsements, contracts, facts and applicable law. Consult qualified professionals.
Constructive Solutions, Inc. is a full-service commercial construction company serving San Francisco and Bay Area.
Whatever your vision, we have the resources, experience, and insight to make your concept a reality, and a space where your business can flourish.
Call Us Now for Estimate

Leave a Reply